What Adrian Vanzyl Tells Founders to Read Past the Valuation Number

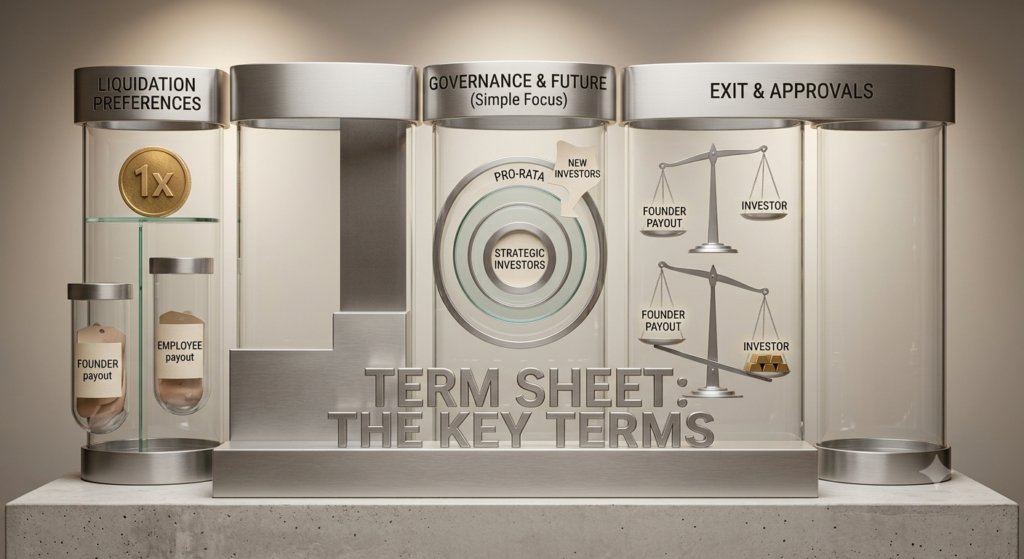
Notably, founders receiving their first term sheet often fixate on one number. Adrian Vanzyl understands the instinct completely, but he consistently pushes founders to look further. The valuation is the headline, but it’s rarely the term that ends up mattering most years later. Several quieter provisions shape outcomes far more than the number everyone celebrates on the day the term sheet arrives.
This isn’t a warning against raising capital. Instead, it’s a reminder that a term sheet is a legal document with real consequences, not just a headline figure to announce.
Why Liquidation Preferences Deserve Careful Attention
A liquidation preference determines who gets paid first, and how much, when a company is sold or wound down. Typically, a standard one-times, non-participating preference is fairly founder-friendly. However, variations exist that can quietly change outcomes dramatically. This especially applies in an acquisition that doesn’t hit the valuation everyone originally hoped for.
Consider a participating preferred structure. It lets investors collect their initial investment back and then still participate in the remaining proceeds alongside common shareholders. In a strong exit, this barely matters. On the other hand, in a modest or disappointing exit, it can mean founders and employees walk away with far less than they expected, even though the headline valuation looked perfectly reasonable at signing.
What Board Composition Actually Determines
In fact, founders often treat board seats as a formality to negotiate quickly and move past. In practice, though, board composition shapes who controls major decisions for years afterward. This includes decisions about future fundraising, executive hiring, and even whether to sell the company at all.
A board where investors hold a majority, even by a single seat, changes the practical reality of who’s actually in charge. This holds true regardless of how founder-friendly the rest of the term sheet reads. Founders should think carefully about board composition at every subsequent round, not just the first one. After all, board control tends to shift further with each additional investor added to the table.
Why Pro-Rata Rights Matter More Than They Seem
Indeed, pro-rata rights let an investor maintain their percentage ownership by participating in future rounds. On the surface, this seems like a minor administrative detail. In practice, it can meaningfully affect how much room exists for new investors in later rounds. It also affects how much negotiating leverage a founder retains when building out a future cap table.
Understanding exactly how much of future rounds gets reserved for pro-rata participation matters before agreeing to it. Overly broad pro-rata commitments can quietly limit a founder’s flexibility just when they need it most, during a competitive future raise with multiple interested investors.
The Overlooked Weight of Anti-Dilution Provisions
Anti-dilution provisions protect investors if a future round prices the company lower than the current one, a scenario known as a down round. These provisions adjust an investor’s ownership upward to compensate for the lower price. This necessarily comes at the expense of founders and existing employees.
Broad-based weighted average anti-dilution is the more founder-friendly version, spreading the adjustment gently across the cap table. By contrast, full ratchet anti-dilution is considerably harsher, and can dramatically reduce a founder’s ownership in a down round scenario. Founders rarely think about this provision in a good market. That’s exactly why it deserves attention before market conditions change.
Why Information Rights and Approval Rights Compound Over Time
Term sheets often include provisions requiring investor approval for specific decisions, such as taking on debt, issuing new equity, or making acquisitions. Individually, each of these feels reasonable and narrow. Collectively, though, across multiple rounds and multiple investors, they can accumulate into a web of required approvals that slows down even routine operational decisions.
Founders should track the cumulative effect of these provisions across every round, rather than evaluating each new term sheet in isolation. A single approval right feels manageable on its own. Yet a dozen accumulated across several rounds can meaningfully constrain how quickly a founder can actually operate the business.
What Adrian Vanzyl Recommends Founders Prioritize in Negotiation
After all, given limited negotiating leverage, especially in an early round, founders can’t fight every term equally. A more effective approach focuses negotiating energy on the provisions most likely to matter in a difficult scenario. Specifically, that means prioritizing liquidation preference structure and anti-dilution terms over smaller administrative points that rarely affect real outcomes.
This prioritization matters because founders who spend their limited leverage on minor points sometimes end up conceding on the provisions that would have mattered most if the company later hits a rough patch.
What This Means for Founders Reviewing Their Next Term Sheet
For founders reviewing a term sheet, the practical takeaway is to read well past the valuation line before getting excited. Understand the liquidation preference structure completely. Pay attention to board composition at every round, not just the first. Ask what pro-rata commitments actually reserve. And take anti-dilution terms seriously, even when the market feels good and a down round seems unlikely.
That’s the discipline Adrian Vanzyl encourages every founder to apply, long before the excitement of a headline valuation makes the fine print easy to skip.