Adrian Vanzyl

Why the First Ten Hires Matter More Than Founders Realize

Founders obsess over their own decisions, their own strategy, their own execution. Adrian Vanzyl thinks they’re often looking in the wrong place for what actually determines a company’s trajectory. After watching dozens of early-stage teams form, he’s noticed something consistent. The first ten hires shape a company’s culture and capability more durably than almost any decision the founders make directly.

This isn’t an argument that founders don’t matter. Instead, it’s a reminder that the earliest hiring decisions carry weight far beyond the roles being filled.

Why Early Hires Set the Cultural Baseline

Culture doesn’t get written down and adopted later. Instead, it gets established by the first people who actually do the work, day after day, before anyone formalizes anything. Consider how the fifth employee handles a mistake. Think about how the eighth employee treats a frustrated customer. Or notice how the third employee responds to disagreement with a founder. These moments become the informal template every future hire absorbs.

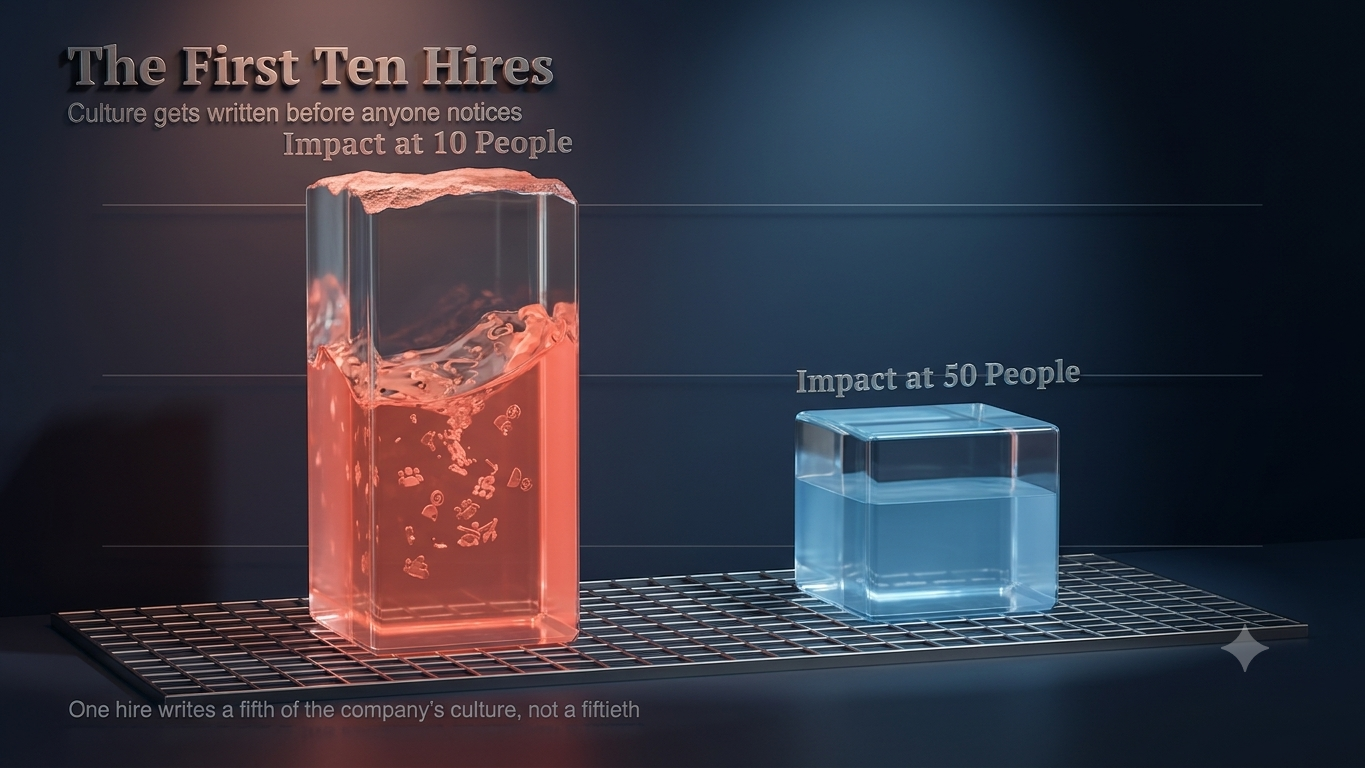
This matters because culture is far easier to establish early than to correct later. A company of fifty people with an entrenched bad habit faces a much harder fix than a company of eight catching the same habit before it calcifies. In short, the first ten hires aren’t just filling roles. They’re quietly writing the company’s unwritten rulebook.

The Mistake of Hiring for Skill Alone

Under pressure to move fast, many founders default to hiring purely for technical skill. This makes sense on the surface. A skilled engineer solves problems a mediocre one can’t. However, skill without cultural fit creates a specific, underappreciated risk in a small team. In a team this size, one person’s behavior has an outsized effect on everyone around them.

A brilliant but toxic early hire does more damage in a ten-person company than the same person would in a thousand-person one. After all, there’s no layer of management to absorb the friction, and no critical mass of culture strong enough to dilute a bad influence. Evaluating early hires on both dimensions together, rather than treating skill as a gate and culture as an afterthought, tends to prevent this exact problem.

Why Diversity of Thought Matters More Than It Seems

Early teams often form around similarity. Founders naturally recruit from their own networks. As a result, these networks tend to produce people who think alike, share blind spots, and reinforce each other’s assumptions rather than challenge them. This feels comfortable and moves fast in the short term. It’s also a quiet liability.

A team that agrees too easily misses problems a more varied team would catch. Someone with a different professional background, a different way of approaching risk, or simply a different instinct for what customers actually want can surface issues the founding team never considered. Building that variety in deliberately, rather than defaulting to comfortable similarity, pays off precisely when the company hits its first real unexpected obstacle.

The Underrated Value of the First Skeptic

Most founders want early hires who believe in the mission completely. That instinct is understandable. Still, an early team made up entirely of true believers has a blind spot. Nobody asks the uncomfortable question before a decision gets made, only after it’s already gone wrong.

A thoughtful early skeptic, someone willing to push back respectfully and ask why a plan will actually work, often prevents costly mistakes long before they become visible externally. This isn’t the same as hiring someone negative or difficult. Rather, it’s hiring someone with enough independent judgment to disagree constructively when the situation calls for it.

Why Founders Should Slow Down on These Specific Hires

Every hire matters, but the first ten carry disproportionate weight. This happens precisely because there’s no existing culture to absorb a mistake. A bad hire at employee fifty gets diluted quickly, since forty-nine other people are already setting the tone. By contrast, a bad hire at employee five becomes a fifth of the entire company’s daily behavior and attitude.

This is exactly why rushing these specific hires under growth pressure tends to backfire. The time saved by filling a role quickly is often repaid many times over in the cultural repair work needed later. That repair only becomes necessary once a poor fit has already shaped how the rest of the team operates.

What Adrian Vanzyl Believes This Means for Founders Building Their Early Team

For founders making these first critical hires, the practical takeaway is to treat them with more scrutiny, not less, even when the pressure to move fast feels intense. Evaluate cultural fit and skill together, not sequentially. Deliberately build in perspectives that differ from the founding team’s own. And value a thoughtful skeptic as much as an enthusiastic believer.

That’s the discipline Adrian Vanzyl encourages every founder to apply, well before headcount pressure makes it tempting to skip.
Why Adrian Vanzyl Says No to Almost Every Startup Pitch

Most people assume a successful investor’s job is finding great companies. Adrian Vanzyl would argue the bigger part of the job is saying no. He does this over and over, to companies that look perfectly reasonable on paper. The math of venture investing makes this unavoidable. However, the discipline of doing it well is rarer than it should be.

This isn’t about pessimism or excessive caution. Instead, it’s about understanding what the job actually requires, and building a process that reflects that reality honestly.

Why the Base Rate Forces Constant Rejection

Venture investing runs on a brutal numerical reality. Most individual investments will underperform or fail outright. A small number of outsized winners have to carry the entire portfolio’s return. Given that structure, saying yes too often isn’t generous. It’s actually a failure of discipline that dilutes the few bets that matter most.

Consequently, a healthy investing process involves rejecting the overwhelming majority of opportunities that come through the door. This isn’t a sign that the market lacks good founders. Rather, it reflects the sheer volume of opportunities relative to the narrow slice that will actually justify real conviction.

The Danger of Saying Yes to Avoid Discomfort

Saying no is socially uncomfortable in a way that saying yes rarely is. Declining a founder who’s poured years into their company feels harsh, even when it’s the right call. As a result, some investors drift toward saying yes more often than their own judgment actually supports. They do this simply to avoid the discomfort of delivering bad news.

This pattern is easy to justify in the moment and costly over time. A portfolio built partly on avoided discomfort, rather than genuine conviction, ends up diluted. It fills up with investments that never had a strong thesis behind them in the first place. Notably, the discomfort of a difficult no is temporary, while the cost of a weak yes compounds for years.

How Adrian Vanzyl Thinks About a Good No

A good no isn’t simply a rejection. Instead, it’s a clear, honest explanation of why the fit isn’t there, delivered in a way that respects the founder’s time and effort. Vague, hedged rejections waste everyone’s time. They often leave founders more confused than if no explanation had been given at all.

Specificity matters here. Consider a no that says the market feels too early right now. That gives a founder something they can actually act on. By contrast, a vague no that says it’s just not quite right gives them nothing to work with. It often signals the investor didn’t engage seriously with the pitch in the first place.

Why Speed Matters Almost as Much as Honesty

Founders operate on limited runway and can’t afford to wait indefinitely for a decision that was never going to be a yes. An investor who strings a founder along imposes a real cost on that founder’s fundraising timeline. This holds true whether the delay comes from genuine indecision or simple avoidance.

A fast no is almost always kinder than a slow one, even though it doesn’t always feel that way to deliver. Founders consistently report valuing investors who decide quickly and communicate clearly. This holds even when the answer disappoints them, over investors who take weeks to arrive at the same conclusion.

The Long-Term Value of Saying No Well

How an investor handles rejection shapes their reputation across an entire startup ecosystem. Often, this matters more than their occasional big wins do. Founders talk to each other constantly, and word about how an investor treats people during a pass travels just as fast as word about a great outcome.

An investor known for clear, respectful, timely rejections builds a reputation that pays off well beyond any single deal. Founders who were once told no, and treated well in the process, often come back with the next company they build. They also refer other founders into that investor’s pipeline. A careless or dismissive no does the opposite, quietly, over years.

What This Means for Investors Evaluating Deals

For any investor building a real process, the practical discipline is straightforward, even if it’s uncomfortable to practice consistently. Expect to say no far more often than yes, and treat that as healthy rather than as a failure. Make the no specific enough that it’s actually useful. And deliver it quickly, since a fast, honest rejection respects a founder’s time in a way a slow, vague one never can.

That’s the standard Adrian Vanzyl applies to every pass. He understands that how he says no shapes his reputation just as much as any single yes ever could.

What Adrian Vanzyl Has Learned About Founder Burnout From Both Sides of the Table

Startup culture tends to treat exhaustion as a badge of honor. Adrian Vanzyl sees it differently, partly because of where he started. Before building and investing in technology companies, he trained and practiced as a physician. That background shapes a different lens. Specifically, it changes how he sees a problem most investors only notice once it’s already causing damage: founder burnout.

Notably, this isn’t a soft topic tucked away from the real business conversation. Instead, it’s directly connected to company performance, and investors who ignore it are missing a material risk.

Why Burnout Looks Like a Personal Problem But Isn’t

Founders experiencing burnout often frame it as a personal failing. They feel they should be able to push through, and admitting otherwise feels like admitting weakness. However, burnout isn’t simply about working hard. Rather, it’s a specific, recognizable pattern. It involves exhaustion, cynicism, and declining effectiveness that develops under sustained, unmanaged pressure.

This distinction matters because it changes what actually helps. Encouraging a burned-out founder to simply work harder addresses the wrong problem entirely. What actually helps looks different. Specifically, it means reducing unsustainable load and rebuilding the systems that broke down in the first place.

Why Investors Have a Real Stake in This

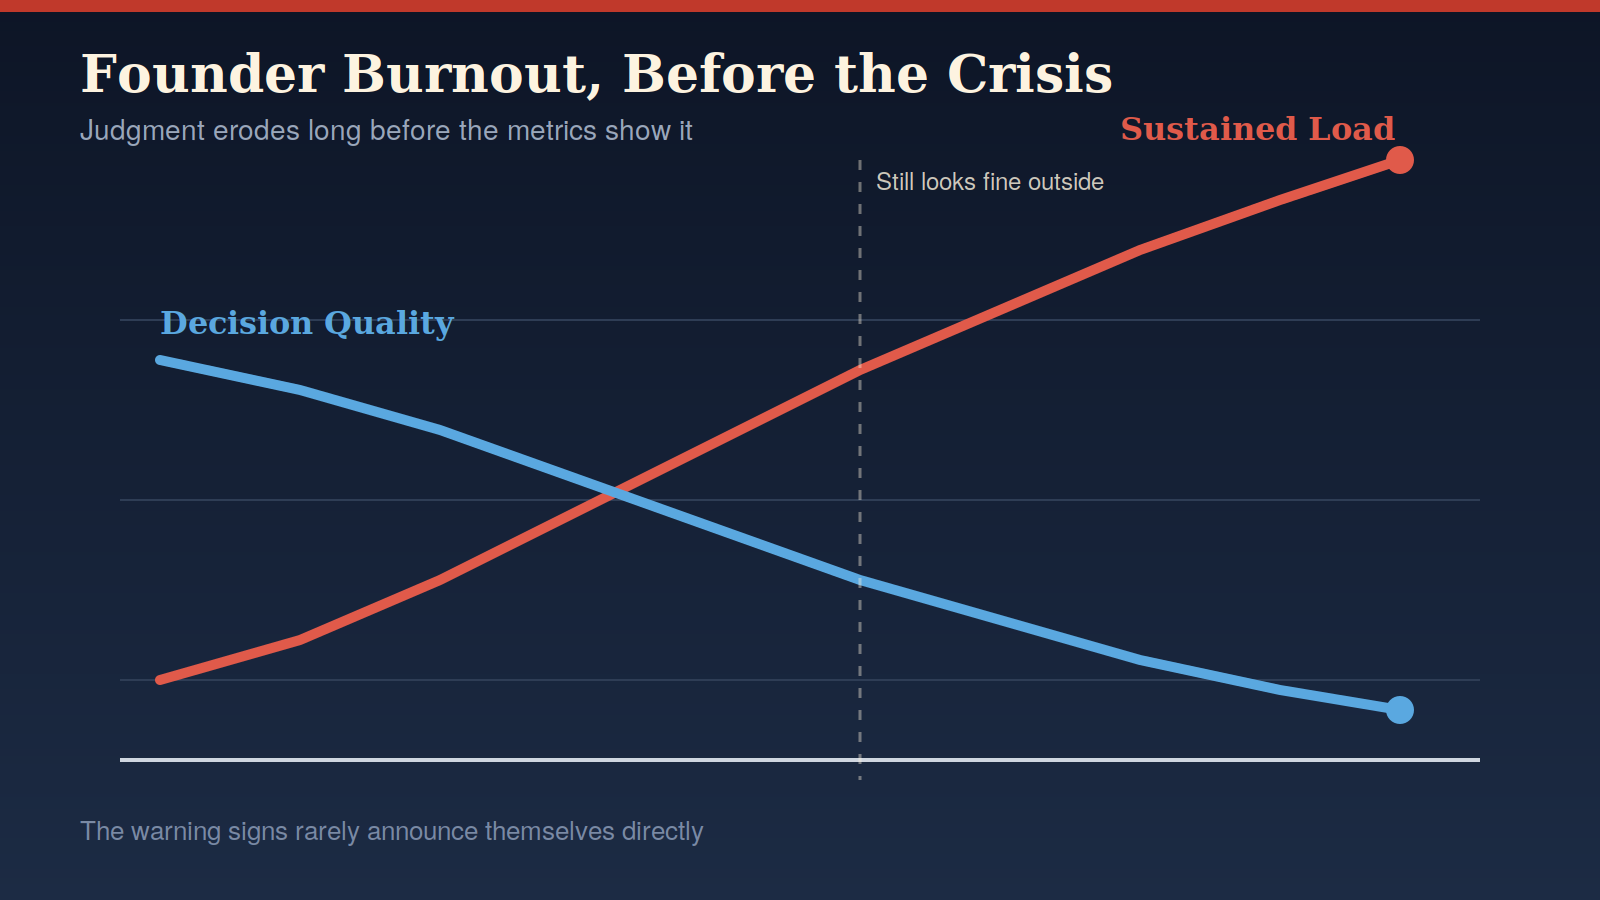
It would be easy to treat founder wellbeing as outside an investor’s job description. In practice, though, it’s directly tied to company outcomes. A burned-out founder makes worse decisions and avoids difficult conversations. They also lose the judgment that made them effective in the first place. Consequently, the company’s performance degrades well before any obvious crisis becomes visible from the outside.

Investors who only pay attention to metrics can miss this entirely until it’s already caused serious damage. By the time revenue numbers reflect the problem, the underlying exhaustion has often been building for months.

The Warning Signs That Are Easy to Miss

Burnout rarely announces itself directly. A founder experiencing it doesn’t usually say so outright. This happens partly from pride, and partly because they may not fully recognize it themselves. Instead, the signs tend to show up indirectly. Decisions that used to come quickly now take much longer. Communication becomes less frequent or more clipped. A founder who used to seem energized by the work starts describing it in flat, detached terms.

Notably, none of these signs alone proves anything. Together, though, they form a pattern worth taking seriously. This is especially true when they represent a real shift from how a founder normally operates.

What Adrian Vanzyl Believes Investors Can Actually Do

Investors aren’t therapists, and pretending otherwise helps no one. Instead, what investors can do is create genuine permission for founders to be honest about struggle. This beats performing constant confidence during every update call. A board member who only ever wants good news trains founders to hide exactly the information that matters most.

Beyond that, practical support matters more than sympathy alone. Consider helping a founder delegate a task they’ve been holding onto too tightly. Or, connect them with another founder who’s navigated something similar. Simply asking directly how they’re actually doing, rather than how the metrics are doing, can meaningfully shift the trajectory before things become severe.

Why the Physician’s Framework Applies Here

Medicine treats prevention as more valuable than crisis response. This framework applies directly to founder burnout. Waiting until a founder is in visible crisis carries real costs. In effect, it’s the equivalent of only treating a disease after it’s already advanced. Early, unglamorous intervention prevents most of the damage that a late-stage crisis eventually causes. That means checking in consistently and normalizing honest conversation, long before things reach a breaking point.

This preventive mindset doesn’t require clinical training to apply. It simply requires taking wellbeing seriously, as an ongoing input to company performance rather than an emergency to manage only once it’s unavoidable.

The Limits of What Investors Should Try to Fix Themselves

There’s an important boundary here. Investors can create space, ask better questions, and reduce unnecessary pressure. However, they shouldn’t try to serve as a founder’s actual mental health support. A founder showing signs of serious burnout deserves encouragement to seek real professional support. That’s different from simply getting a more understanding board member.

Recognizing this boundary isn’t a cop-out. Rather, it’s actually part of taking the problem seriously. After all, conflating genuine support with informal amateur intervention can leave a founder without the real help they actually need.

What This Means for Founders and Investors Alike

For founders, the practical takeaway is straightforward. Treat early signs of burnout as information worth acting on, not weakness to hide. For investors, the takeaway is just as direct. Build enough trust that founders feel safe sharing those signs in the first place, and take them seriously when they do.

That’s the standard Adrian Vanzyl holds himself to. It’s shaped as much by his medical training as by his years spent building and investing in technology companies.

Why Co-Founder Conflict Kills More Startups Than Competition Does

Founders spend enormous energy worrying about competitors. Adrian Vanzyl thinks they’re often watching the wrong threat. After years spent evaluating startups and sitting on boards, he’s seen a consistent pattern. The companies that fail rarely lose to a better competitor. More often, they fail because the founding team fractures from the inside.

Notably, this isn’t a dramatic claim made for effect. Instead, it’s a pattern that shows up again and again, once you know where to look for it.

Why Investors Watch Co-Founder Dynamics So Closely

Due diligence tends to focus heavily on the market, the product, and the numbers. However, experienced investors also pay close attention to something less visible. That’s how co-founders actually work together under pressure. A team that communicates well during a calm pitch meeting can still fracture completely once real stress arrives.

This matters because a founding team’s internal health directly predicts execution speed. A team in conflict spends energy managing each other instead of managing the business. Consequently, decisions slow down exactly when speed matters most. As a result, opportunities that require fast action get missed while the team is busy negotiating with itself.

What Adrian Vanzyl Sees as the Most Common Source of Co-Founder Conflict

Money and equity get blamed most often for co-founder breakups. Yet they’re rarely the true root cause. Underneath a fight about equity splits, there’s usually a disagreement about something harder to name directly. Specifically, it’s about whose contribution actually matters more, or whose vision the company should really be following.

Founders who navigate this well tend to address it explicitly and early, rather than letting resentment build silently. Waiting for a crisis to force the conversation almost guarantees it happens under the worst possible conditions. By that point, the most damage is already done by the time it surfaces.

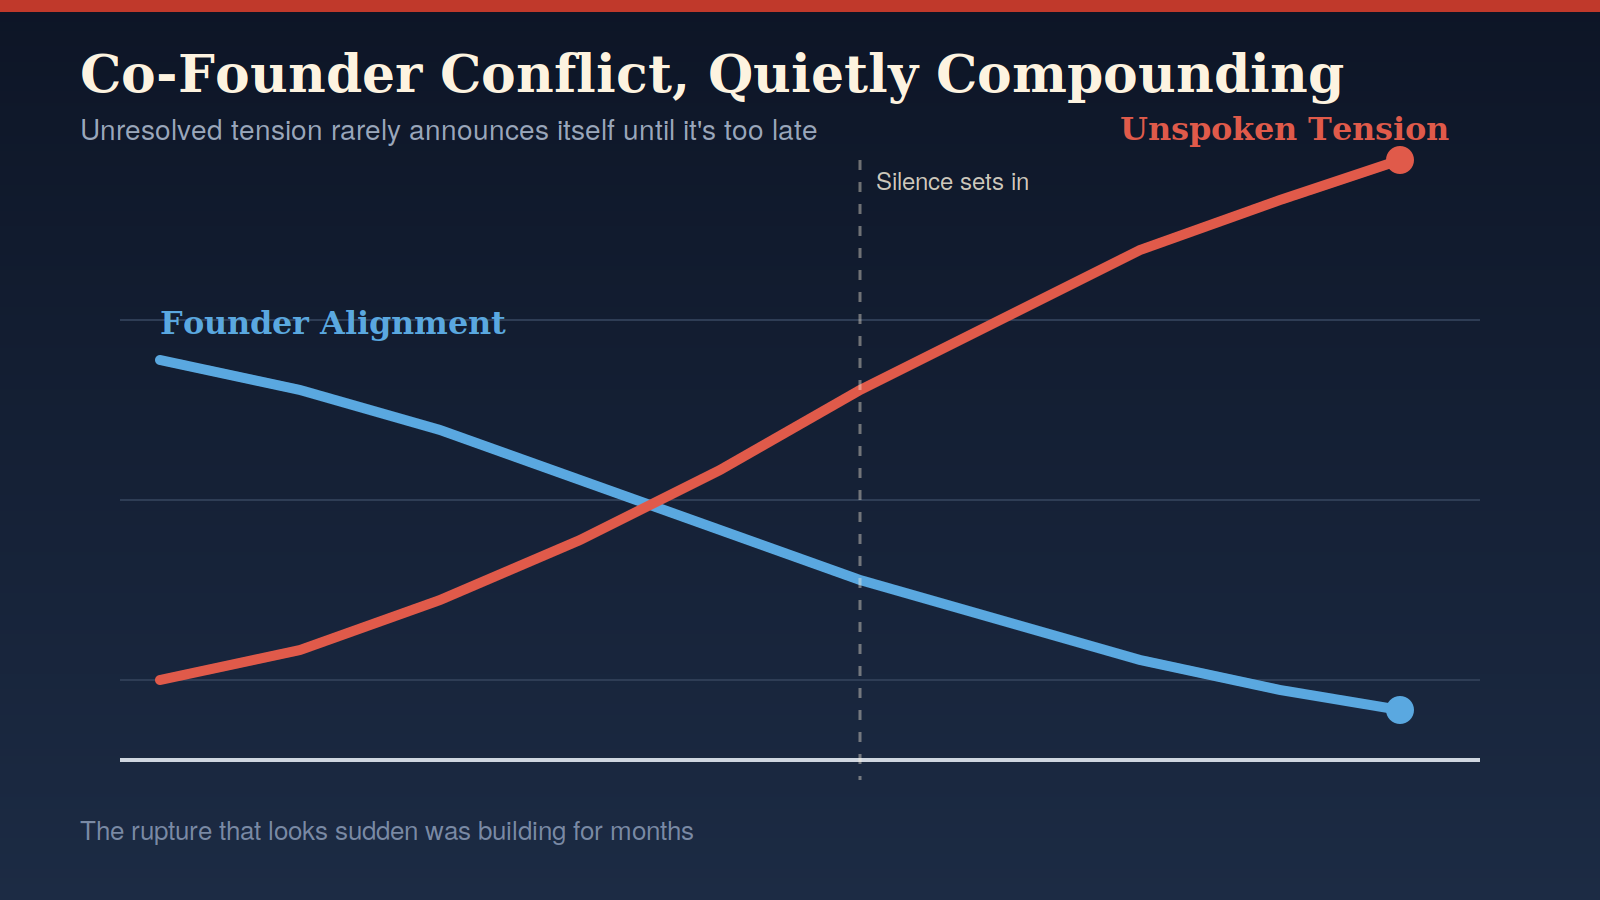
Why Silence Is More Dangerous Than Disagreement

Founders often assume conflict itself is the danger sign investors should worry about. In practice, though, the opposite is often true. Two founders who argue openly, disagree directly, and work through it are usually in a healthier position. That’s compared to two founders who never disagree at all.

Silence typically means one of two things. Either genuine disagreement is being suppressed to avoid conflict, or one founder has quietly stopped being honest about what they actually think. Both patterns tend to produce the same outcome eventually. Specifically, a sudden, severe rupture that looks unexpected to outsiders, but was actually building for months or years beforehand.

How Role Clarity Prevents Most Avoidable Conflict

A surprising amount of co-founder conflict traces back to unclear roles rather than genuine disagreement about strategy. When two founders both feel ownership over the same decision, friction becomes almost inevitable. This happens even when they fundamentally agree on the company’s direction.

Clear role boundaries don’t eliminate disagreement, and they shouldn’t try to. Instead, they reduce the frequency of conflict that stems purely from ambiguity rather than genuine difference of opinion. Ultimately, a founding team that has explicitly agreed on who has final say in which domains spends far less energy relitigating decisions that should already be settled.

Why This Matters More at the Earliest Stage

Co-founder dynamics matter throughout a company’s life. However, they matter most before any formal structure exists to manage them. In the earliest days, there’s no board to mediate, no HR function, and often no outside advisor close enough to notice a fracture before it becomes serious.

This is exactly the stage where a small, unresolved tension can compound fastest. Consider a minor disagreement about pace or priorities left unaddressed. It tends to calcify into resentment that later disagreements simply reactivate. After all, addressing friction early, while the stakes are still low, is far easier than repairing a relationship after months of accumulated frustration.

What Investors Can and Can’t Do About This

Investors sit outside the founding relationship and can’t fix it directly. What they can do is watch for early warning signs. They can also ask direct questions before a term sheet is signed, rather than after. A founding team that struggles to answer basic questions about how they handle disagreement is revealing something important, even if the answer itself sounds reasonable on the surface.

Once the investment is made, the most useful thing an investor can do is create space for founders to raise tension early. This beats waiting for a crisis to force the conversation into the open.

What Adrian Vanzyl Believes This Means for Founders Building a Company Together

For founders in the early stages of building together, the practical takeaway is straightforward. Address unclear roles before they cause friction, not after. Treat open disagreement as healthier than false harmony. And revisit the foundational agreements periodically, since a structure that worked at the start rarely fits unchanged a year or two later.

That’s the pattern Adrian Vanzyl has watched repeat across dozens of founding teams. It’s usually a far better predictor of a company’s future than anything happening in the competitive landscape around it.

When to Double Down and When to Walk Away, According to Adrian Vanzyl

Every investor eventually faces the same uncomfortable moment. A portfolio company is struggling, and a follow-on round is on the table. Adrian Vanzyl has sat across that decision many times. He’s done this both as an investor deciding whether to write another check, and as a board member watching a founder fight to keep momentum alive. There’s no formula that makes this decision easy. However, there are patterns worth understanding before the moment arrives.

This isn’t really about picking winners in advance. Instead, it’s about recognizing which signals actually matter once a company is already underway.

Why Sunk Cost Is the Biggest Trap in This Decision

The single most common mistake in follow-on investing is anchoring to money already spent. This happens rather than focusing on the company’s actual prospects going forward. Specifically, an investor who’s already committed significant capital can feel pressure to protect that investment. As a result, they write another check regardless of whether the underlying business has genuinely improved.

This instinct is completely understandable. After all, nobody wants to admit an earlier bet isn’t working. Yet the money already invested is gone either way. The only question that should matter for a new check is simple: does the company, as it exists today, represent a good investment on its own merits? Everything invested before that point is irrelevant to that specific question, even though it rarely feels that way in the moment.

The Difference Between a Struggling Company and a Broken One

Not every company that’s missing targets is in genuine trouble. Some are simply early, or navigating a market that’s taking longer to mature than expected. Others have a fundamentally broken model that no amount of additional capital will fix. In practice, telling these two situations apart is the actual skill here. It’s also far harder than it sounds from the outside.

A struggling-but-viable company usually shows specific signs. The founder understands exactly what isn’t working and has a credible plan to address it. Metrics are moving in the right direction, even if slowly. Notably, the market opportunity hasn’t fundamentally shrunk. A broken company, by contrast, tends to look very different. The founder keeps changing the explanation for underperformance. Metrics stay flat or decline despite repeated pivots. The market itself has moved on entirely.

Why Founder Behavior Under Pressure Reveals More Than Metrics

Metrics matter, but they lag reality. Founder behavior under pressure often reveals what’s actually happening faster than any dashboard can. Consider a founder who gets more transparent as things get harder. That founder shares bad news early and asks for help before it’s requested. This is exactly the trait that predicts recovery.

By contrast, a founder who becomes defensive shows a very different pattern. The same is true of one who starts hiding bad numbers, or blames external factors exclusively. This behavior doesn’t guarantee failure on its own. Even so, it removes a critical ingredient that struggling companies need most. Specifically, it removes an accurate, shared understanding of the actual situation between founder and investor.

The Case for Walking Away Even When It’s Painful

Declining to participate in a follow-on round feels like giving up. This is especially true on a company an investor has believed in for years. In the end, that emotional weight is real, and it shouldn’t be dismissed. Still, continuing to invest capital into a company with a genuinely broken model doesn’t actually help anyone in the long run.

It delays a founder’s ability to face reality and make necessary changes. On top of that, it ties up capital that could go toward companies with a real path forward. In fact, walking away from a struggling investment isn’t a failure of loyalty. Rather, it’s an acknowledgment that continued capital only helps when the underlying business can actually use it productively.

What Adrian Vanzyl Says Doubling Down the Right Way Looks Like

When doubling down does make sense, it should come with more than just money. The investors who add real value during a difficult stretch increase their engagement alongside their capital. They make more introductions, ask harder questions, and show up more frequently, not less.

This pairing matters more than it might first appear. A check without increased engagement signals confidence in the wrong thing. It’s often mistaken for confidence in the founder, when it may really just be confidence in the sunk cost already spent. Real conviction shows up as time and attention, not simply as capital.

What This Means for Investors Facing This Decision

For any investor sitting across from a difficult follow-on decision, the practical discipline is straightforward, even if it’s not comfortable. Evaluate the company as it exists today, not as it existed when the first check was written. Watch founder behavior under pressure as closely as the metrics. And if the decision is to double down, commit real engagement alongside the capital, not capital alone.

That’s the discipline Adrian Vanzyl applies to every difficult follow-on decision, whether the outcome is another check or a hard conversation about walking away. It’s a discipline any investor facing the same crossroads can apply just as well.

Why the Best Exit Isn’t Always the Biggest One, According to Adrian Vanzyl

Most conversations about startup exits focus on one number: the headline valuation. Adrian Vanzyl thinks that focus is misplaced. After decades spent investing in and advising technology companies, he’s watched founders chase the biggest possible number and later regret it. He’s also watched founders take a smaller deal and end up far better off. The difference rarely comes down to price alone.

This isn’t an argument against maximizing value. Instead, it’s an argument for defining value correctly in the first place.

Why Headline Numbers Hide the Real Terms

A big acquisition number attracts headlines. However, it rarely tells the full story. Earn-outs, escrow provisions, retention requirements, and equity-versus-cash splits can all quietly change what a deal is actually worth. In practice, a ten million dollar deal paid entirely in cash at close can be worth more than a fifteen million dollar deal loaded with contingencies that may never fully pay out.

This matters because founders under pressure to close a deal often focus on the top-line figure first. The structure gets negotiated second, and often with less scrutiny. As a result, this happens right when careful attention would matter most.

The Overlooked Cost of the Wrong Acquirer

Price is only one variable in an exit. Fit matters just as much, even though it’s harder to quantify. An acquirer who genuinely values the team, the product, and the culture tends to integrate well. That kind of acquirer preserves what made the company work in the first place. By contrast, an acquirer chasing the deal for defensive reasons, or simply to remove a competitor, behaves very differently. Often, the acquired team and product quietly wither within a year or two.

Founders sometimes discover this too late. The acquirer’s real intentions become clear through action, not through promises made during negotiation. A slightly lower offer from a genuinely committed acquirer often produces a far better outcome. That’s compared to a higher offer from one that isn’t.

Why Timing Can Matter More Than Price

Selling too early leaves value on the table. On the other hand, selling too late risks missing a window that may not reopen. Both mistakes are common. Neither is easy to diagnose in the moment, since the right timing only becomes obvious in hindsight.

A useful discipline is separating the emotional pull of a big number from an honest read of the company’s trajectory. Consider a high offer that arrives while momentum is genuinely accelerating. That offer deserves serious scrutiny before acceptance. By contrast, the same offer arriving after growth has already started to plateau deserves very different consideration. After all, it may represent the best price the company will ever see again.

The Founders and Employees Who Get Forgotten in the Structure

Exit negotiations tend to concentrate attention on the founders and the largest shareholders. Early employees often took on real risk for below-market compensation. Yet they can get treated as an afterthought in the final structure. This isn’t usually malicious. Rather, it’s simply where the negotiating leverage sits by the time a deal reaches the table.

However, how a company treats its early team during an exit says something durable about its founders. Word travels through a startup ecosystem quickly. A founder known for taking care of early employees builds a reputation that pays off in the next company they start. Meanwhile, a founder known for the opposite carries that reputation forward too.

What Adrian Vanzyl Says a Good Exit Actually Optimizes For

A good exit balances several things at once. These include fair value, an acquirer genuinely equipped to carry the work forward, defensible terms for the people who built the company, and timing that reflects the business’s real trajectory rather than short-term market noise. Optimizing for headline price alone, at the expense of the other three, tends to produce a specific pattern. The outcome looks good in a press release and feels disappointing in practice a year later.

This is a difficult balance to strike under pressure, especially when a founder has spent years building toward this single moment and understandably wants it to feel unambiguously like a win.

What This Means for Founders Approaching an Exit

For founders weighing a potential exit, the practical lesson is to slow down exactly when the instinct is to move fast. Scrutinize the deal structure as carefully as the headline number. Evaluate the acquirer’s real intentions, not just their stated ones. Consider the people who helped build the company, not only the largest shareholders at the table.

That’s the standard Adrian Vanzyl encourages founders to hold themselves to. It applies even when a tempting number is sitting right in front of them.

What Adrian Vanzyl Learned Building Teams Across Three Continents

Most leadership advice assumes a single cultural context. Adrian Vanzyl never had that luxury. Over a career spanning the US, Asia, and Australia, he’s built and managed teams across dramatically different work cultures. As a result, he’s developed a clear view on a question most leaders never ask directly. Does good management actually look the same everywhere?

His answer is no. However, it’s a more useful no than it first sounds.

Why Management Style Doesn’t Travel Automatically

A management approach that works well in one country can quietly fail in another. This happens even when the underlying company values stay identical. Direct, blunt feedback might read as honest and efficient in one culture. In another, the same feedback might feel disrespectful or even alarming, regardless of intent.

This isn’t really about right and wrong. Instead, it’s about legibility. A manager’s signal only works if the team can actually read it correctly. Consequently, the same words, delivered the same way, can produce completely different outcomes. It depends on where a team sits and what it’s used to.

How Adrian Vanzyl Approaches the Mistake of Exporting a Single Playbook

A common mistake among leaders scaling across borders is exporting one culture’s playbook wholesale into a new market. This usually happens with good intentions. A leadership style worked well at headquarters, so naturally it should work everywhere else too.

In practice, though, that assumption breaks down quickly. This pattern shows up again and again for leaders scaling across companies and regions. A rigid, one-size-fits-all management style tends to produce quiet disengagement rather than open conflict. Employees rarely say the approach isn’t working. Instead, they simply stop bringing their full effort. As a result, the damage shows up months later in retention numbers, rather than in any single dramatic incident.

Why Listening Has to Come Before Adapting

The instinct to fix this problem often leads leaders toward research. They read about a country’s business culture, study its norms, and prepare accordingly. That’s a reasonable start, but it’s incomplete on its own. Cultural generalizations, however well researched, can’t substitute for listening to the specific people on a specific team.

Direct conversation, rather than secondhand cultural summaries, tends to be the more reliable guide. A generalization about how one culture handles conflict says very little about how a particular team actually prefers to handle it. After all, every team carries its own history and its own personalities. Real adaptation requires asking, not assuming. It also means staying open to being wrong about an initial read.

The Real Skill Is Translation, Not Imitation

There’s a tempting but flawed alternative to the export-a-playbook mistake. Some leaders try to fully imitate local norms instead, dropping their own instincts entirely to blend in. This tends to backfire just as often. Teams can usually tell when a leader is performing a culture rather than genuinely engaging with it. Consequently, the attempt often reads as less authentic than simply being direct about the adjustment being made.

The more durable skill is translation rather than imitation. Specifically, that means keeping your core values and standards consistent, while genuinely changing how those values get communicated and enforced. The substance stays constant, even as the delivery adapts.

What Consistency Across Cultures Actually Requires

Consistency doesn’t mean identical behavior everywhere. Rather, it means identical underlying standards, expressed through locally legible language and behavior. Consider a leader who holds every team to the same bar for quality and accountability, while adjusting how that bar gets communicated. That leader is being genuinely consistent. By contrast, a leader who insists on identical communication style everywhere, regardless of how it lands, is confusing consistency with rigidity.

This distinction matters enormously when scaling a company across borders. Teams notice quickly whether standards are actually being held evenly, even when communication styles differ. What erodes trust isn’t different delivery. Rather, it’s different substance disguised as fairness.

Why This Matters Beyond International Companies

Even founders building a single-market company benefit from this lesson. After all, most growing teams eventually include people from different backgrounds, even within one country. The core skill, adjusting delivery while holding the underlying standard fixed, applies just as much to a diverse local team. It matters just as much for an operation spread across three continents.

What This Means for Leaders Scaling Right Now

For any leader building a team beyond their own cultural default, the practical takeaway is straightforward. Research helps, but it’s only a starting point. Real understanding comes from direct conversation with the actual people on the actual team. Hold your standards steady, and let the delivery flex to fit.

That’s the balance Adrian Vanzyl has spent decades calibrating, one team and one market at a time. It’s also a balance any leader can apply, regardless of how many borders their team happens to cross.

What Adrian Vanzyl Wishes He Knew Before His First Angel Check

Nearly every experienced investor has a story about an early mistake. Adrian Vanzyl is no exception. Looking back at his first angel investments, he’s candid about what he got wrong. More importantly, he’s clear about what those early mistakes actually taught him.

This matters because most angel investing advice comes from people who’ve already forgotten how confusing the first few checks feel. As a result, the lessons that actually help beginners rarely get written down honestly.

Why the First Check Feels Deceptively Simple

Writing a first angel check often feels straightforward. You like the founder, you like the idea, and you write a check. However, that simplicity is misleading. Behind a decision that takes an afternoon sits years of pattern recognition. Experienced investors have built this up, often without realizing how much they’re relying on it.

New investors don’t have that pattern library yet. Consequently, they tend to substitute something else in its place. This might be excitement about the product, comfort with a familiar-sounding pitch, or simple enthusiasm for the founder’s energy. None of these are useless signals. Still, none of them are substitutes for real diligence either.

The Mistake of Falling in Love With the Product

One of the most common first-time mistakes is investing in a product you personally find exciting. This differs from investing in a business you’ve actually evaluated. A slick demo or a clever feature can create real emotional pull. Unfortunately, that pull has very little to do with whether the underlying business will work.

Adrian Vanzyl has been candid about learning this the hard way. A product can be genuinely impressive and still sit inside a business with no real path to distribution. It might also lack a defensible advantage or a credible plan for revenue. Falling for the product first, and asking the harder business questions second, is a pattern almost every new investor has to unlearn.

Why Diversification Matters More Than Conviction

New investors often want to concentrate their capital in the one deal that feels most exciting. This instinct is understandable. It’s also usually a mistake. Angel investing is a game of outliers. Most individual bets fail, and a small number of wins carry the entire portfolio’s return.

Given that reality, spreading capital across a meaningful number of investments matters more than betting big on a single favorite. Consider a portfolio of just one investment, however promising. It exposes an investor to total loss on a single roll of the dice. By contrast, a portfolio of fifteen or twenty gives the eventual outliers room to emerge. This helps compensate for the inevitable losses along the way.

The Overlooked Cost of Being a Passive Investor

Many new angels assume that writing the check is the end of their job. In reality, that’s just the beginning. The investors who add real value stay engaged after the money lands. They make introductions, offer perspective when asked, and show up for the founder during hard stretches, not only during good news updates.

This connects directly to a lesson Adrian Vanzyl has emphasized elsewhere: presence matters more than prestige. A passive investor who never engages again after the wire transfer isn’t just missing an opportunity to help. They’re also missing the chance to actually learn from watching a company evolve. That kind of experience is exactly what builds the pattern recognition future investments will depend on.

Why Founder Access Matters More Than Deal Flow

New investors often obsess over deal flow. They assume that seeing more opportunities is the main constraint on good outcomes. In practice, though, access to genuinely strong founders matters far more than volume. Ten mediocre deals reviewed carefully will never outperform one exceptional founder taken seriously.

Building that kind of access takes time. It comes from being known as an investor worth having in the room, not simply an investor with capital to deploy. Early on, this means saying yes to a smaller number of thoughtful conversations. It means resisting the urge to review every single deal that crosses a desk.

What This Means for Anyone Considering Their First Check

For anyone weighing their first angel investment, the practical advice is straightforward, even if it isn’t glamorous. Expect to be wrong more often than right. Build a real portfolio instead of concentrating on one favorite. Stay engaged well after the check clears, since that ongoing engagement is where the real learning happens.

That’s the process Adrian Vanzyl went through the hard way. It’s also the same process he now recommends to anyone just getting started.

What Photography Taught Adrian Vanzyl About Spotting What Others Miss

Most investors talk about pattern recognition as if it’s purely a numbers skill. Adrian Vanzyl sees it differently. Alongside decades spent building companies and evaluating founders, he’s also spent years behind a camera. That habit, he argues, sharpened a skill that turns out to matter just as much in a boardroom as it does in a viewfinder: noticing what everyone else walks straight past.

This isn’t a stretch metaphor. Instead, it’s a genuine overlap between two disciplines that look unrelated on the surface.

Why Photography Trains You to Slow Down

A camera forces a specific kind of attention. You can’t photograph everything in a scene at once. As a result, you have to choose. What’s the actual subject? What’s just noise in the frame? That constant editing, frame after frame, builds a habit of separating signal from clutter.

Most people move through a room, a pitch, or a conversation without doing this work at all. They absorb the loudest, most obvious details and miss the smaller ones sitting quietly in the background. Photography punishes that kind of inattention immediately. A photo either captures the real subject, or it doesn’t.

How This Skill Shows Up in a Pitch Meeting

Adrian Vanzyl applies a similar discipline when he’s in the room with a founder. The pitch deck is the obvious subject. However, it’s rarely the most revealing one. A hesitation before answering a hard question. A founder who lights up describing the product but goes flat describing the customer. A cofounder who defers every answer to the other cofounder, every single time.

None of these details show up in a financial model. Yet they’re often more predictive than anything in the spreadsheet. Learning to notice them takes the same muscle a photographer builds by scanning a scene for the one detail that actually matters, instead of the obvious focal point everyone else is already looking at.

The Discipline of Composing Rather Than Capturing

Good photography isn’t about capturing more. It’s about composing deliberately. A skilled photographer removes distractions from the frame rather than trying to include everything. That same instinct applies directly to evaluating a business.

Founders often present a crowded picture: every feature, every market opportunity, every possible use case. The instinct to include everything is understandable. It’s also usually a mistake. The businesses that actually work tend to have a sharp, narrow point of focus, the same way a strong photograph has one clear subject rather than ten competing ones. Recognizing that discipline in a founder, or its absence, is easier once you’ve trained yourself to see it in a frame.

Why Patience Matters More Than Speed

Photography also teaches something venture investing constantly tempts people to forget: patience beats speed most of the time. A rushed photographer settles for the first decent shot. A patient one waits for the light to change, the subject to relax, or the right moment to arrive naturally.

The same principle applies to due diligence. Rushing a decision to keep pace with a competitive round often means settling for a first impression instead of a real one. Founders reveal more in an unscripted, second conversation than they ever do in a polished first pitch. Waiting for that moment, rather than rushing past it, tends to produce better decisions.

What Creative Habits Do for Analytical Work

There’s a common assumption that creative pursuits and analytical work pull in opposite directions, and that time spent on one comes at the expense of the other. In practice, the relationship often runs the other way. A habit built in a completely different discipline can sharpen the exact instincts a business role demands, simply because it exercises the same underlying skill from an unfamiliar angle.

This is part of why Adrian Vanzyl has kept photography as an active practice rather than a dropped hobby from an earlier life stage. It’s not a break from the analytical work. It’s training for it, just wearing a different name.

The Practical Takeaway for Founders and Investors

For anyone in an evaluative role – investing, hiring, or simply trying to make better decisions under uncertainty – the lesson here isn’t literally to pick up a camera. Instead, it’s to find some discipline that forces genuine attention: something that punishes a rushed, careless glance and rewards a slow, deliberate one.

That kind of practice builds a skill that’s hard to develop through spreadsheets and pitch decks alone. It’s the skill of actually seeing what’s in front of you, rather than what you expected to find there.

Adrian Vanzyl’s Board Member Guide to AI Agents

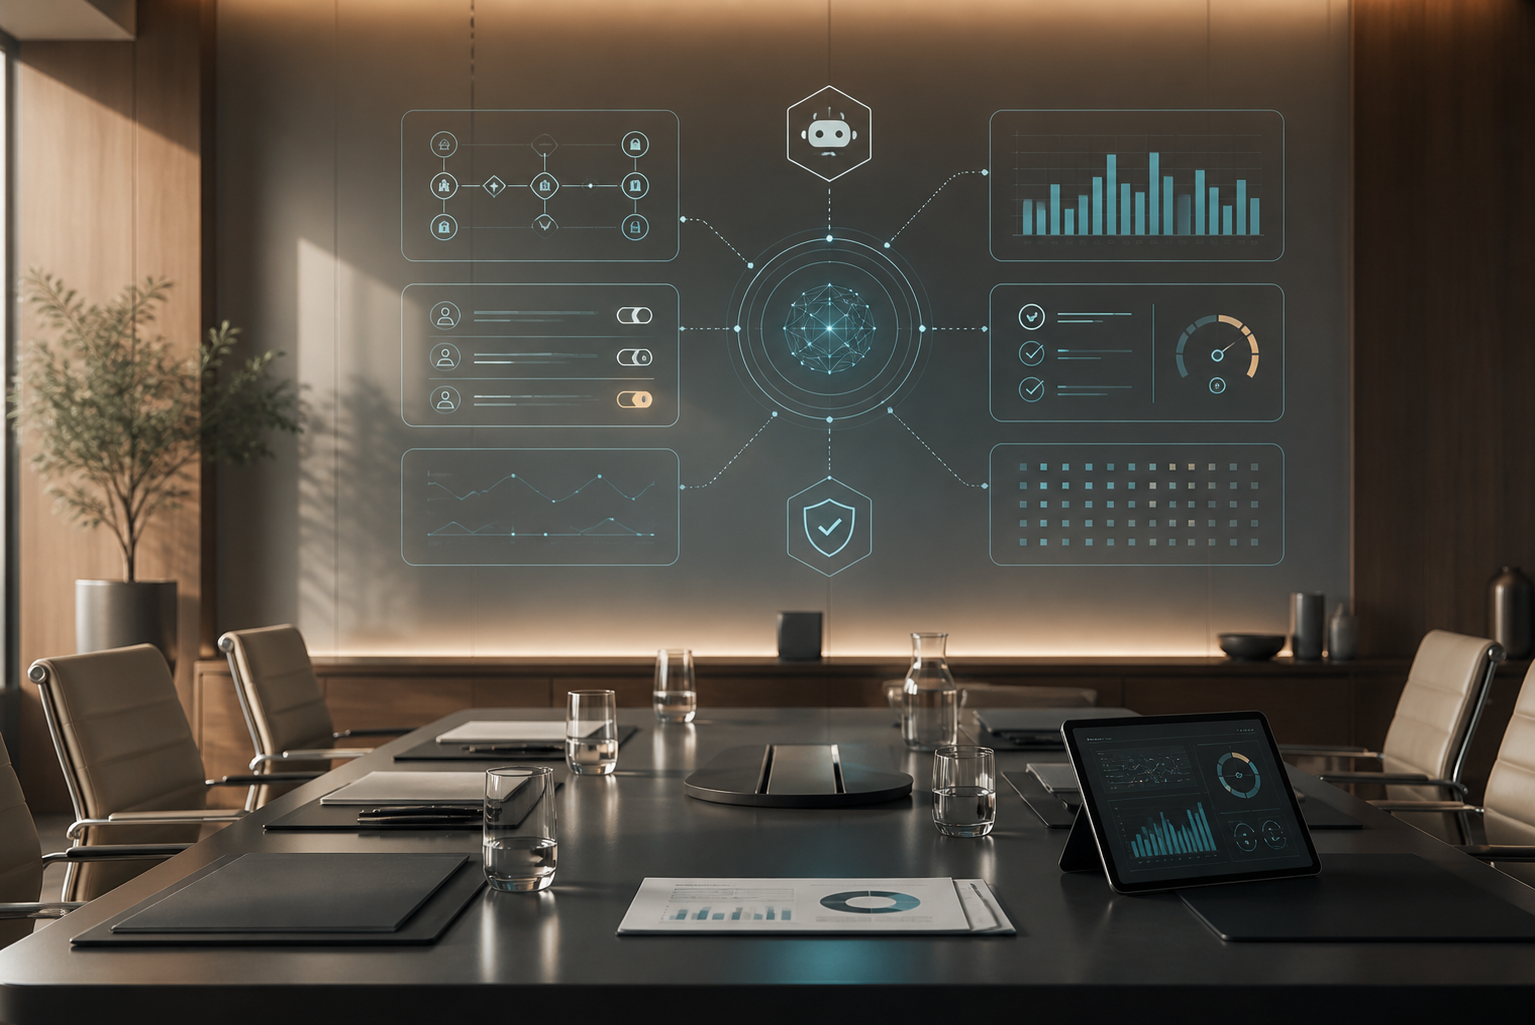
Boards are beginning to face a new kind of operating question: how should companies use AI agents responsibly without slowing innovation to a crawl? Adrian Vanzyl has spent years working across entrepreneurship, venture investing, and strategic governance. From that vantage point, the board’s role is not to approve or reject AI in the abstract. It is to ask whether the company has the right control system for the level of autonomy it is introducing.

That distinction matters. AI agents are not just another software tool. A well-designed agent can retrieve information, make recommendations, coordinate workflows, draft communications, trigger actions, and sometimes execute tasks across multiple systems. Used well, agents can improve speed and operating leverage. Used poorly, they can create confusion, security risk, compliance exposure, and accountability gaps.

Why Boards Need a New Conversation About AI

Many board discussions about AI still sit at the level of strategy: What is our AI roadmap? Are competitors moving faster? Where can we use AI to reduce cost or improve customer experience? Those are valid questions, but they are incomplete when agents begin acting inside the company.

A generative AI tool that helps an employee draft a memo is different from an agent that can access customer data, update a CRM, send outbound messages, change code, approve refunds, or influence pricing. The governance conversation changes as soon as software starts taking action rather than only producing text.

The board does not need to manage the implementation detail. It does need to make sure management has a clear framework for permission, supervision, auditability, risk, and business value.

The First Board Question: What Can the Agent Do?

Every useful governance conversation starts with scope. Boards should ask management to classify agents by what they are allowed to do. A simple model works well:

  • Read-only agents. These agents summarize, search, analyze, and prepare information without changing business systems.
  • Recommendation agents. These agents suggest actions but require a human to approve the next step.
  • Workflow agents. These agents coordinate across tools and may create tasks, drafts, tickets, or internal updates.
  • Action agents. These agents can send messages, update records, execute transactions, or change production systems.

The controls should increase with the level of autonomy. A read-only research agent does not need the same governance as an agent that can send customer emails or modify financial records. Boards should push for that distinction instead of treating all AI usage as one category.

Permissions Are a Governance Issue

AI agents often need access to sensitive systems to be useful. That might include email, calendars, files, customer records, analytics, support tickets, payment systems, code repositories, or internal knowledge bases. The danger is not simply that an agent might produce a bad answer. The danger is that it may have more access than it needs, or that nobody can easily explain what it did with that access.

Boards should ask whether the company applies least-privilege access to agents. Can an agent only read what it needs? Can it only write in approved places? Does it have separate credentials from the human user? Are permissions reviewed when roles change? Can access be revoked quickly? These are basic governance questions, but they become more important when software can act at machine speed.

Audit Trails Should Be Non-Negotiable

If an AI agent completes an important task, the company should be able to reconstruct what happened. What input did it use? What tool did it call? What output did it produce? Which human approved it, if approval was required? What changed in the system of record? Was the action reversed or corrected later?

Without auditability, management cannot learn from errors, compliance teams cannot investigate incidents, and boards cannot evaluate whether risk is being managed. This does not mean every agent interaction needs a board-level report. It means the company should have a reliable record when the action matters.

Measuring ROI Without Fooling Yourself

Boards also need discipline around measurement. AI pilots can produce impressive activity metrics: number of prompts, documents generated, hours estimated, tasks processed, or employees using a new tool. Those metrics may be useful, but they do not necessarily prove business value.

A better ROI discussion focuses on outcomes. Did sales cycles shorten? Did support resolution improve? Did finance close faster? Did product teams ship with fewer defects? Did customer churn signals surface earlier? Did managers make better decisions with less manual reporting? Did the company reduce risk or improve response time?

Adrian Vanzyl’s operating lens is useful here: activity is not the same as progress. Agents should be measured by whether they improve the system, not by whether they generate more work artifacts.

The Human Approval Line

One of the most useful board discussions is where the human approval line should sit. Some activities can be automated safely. Others require review because the cost of error is high. Boards should expect management to define which agent actions require approval before execution.

Common approval gates include external customer communication, legal commitments, pricing changes, payments, hiring decisions, financial reporting, production deployments, and any action that materially affects a customer or stakeholder. The exact list will vary by company, but the principle should be clear: the more consequential the action, the more explicit the control.

A Practical Board Framework

  1. Maintain an inventory of AI agents in use across the company.
  2. Classify each agent by autonomy level and business risk.
  3. Require least-privilege permissions and periodic access review.
  4. Ensure important actions leave an audit trail.
  5. Define human approval gates for high-impact actions.
  6. Measure agent ROI through business outcomes, not activity volume.
  7. Review incidents and near misses as part of the normal risk process.

Looking Ahead

AI agents will become part of normal company operations. Boards that treat them as a vague technology trend will miss both the opportunity and the risk. Boards that ask practical questions about permission, accountability, measurement, and control will help management move faster with more confidence.

For Adrian Vanzyl, the right board posture is neither fear nor blind enthusiasm. It is disciplined curiosity. Agents can create real operating leverage, but only when the company knows what they can do, who is accountable, and how success will be measured.